8 min read
Quick Summary
- Three friends with the same income buy the same ₹50 lakh car: Mehul pays cash, Nirav and Kunal borrow 80% at 7.5% for 5 years and keep the rest invested.
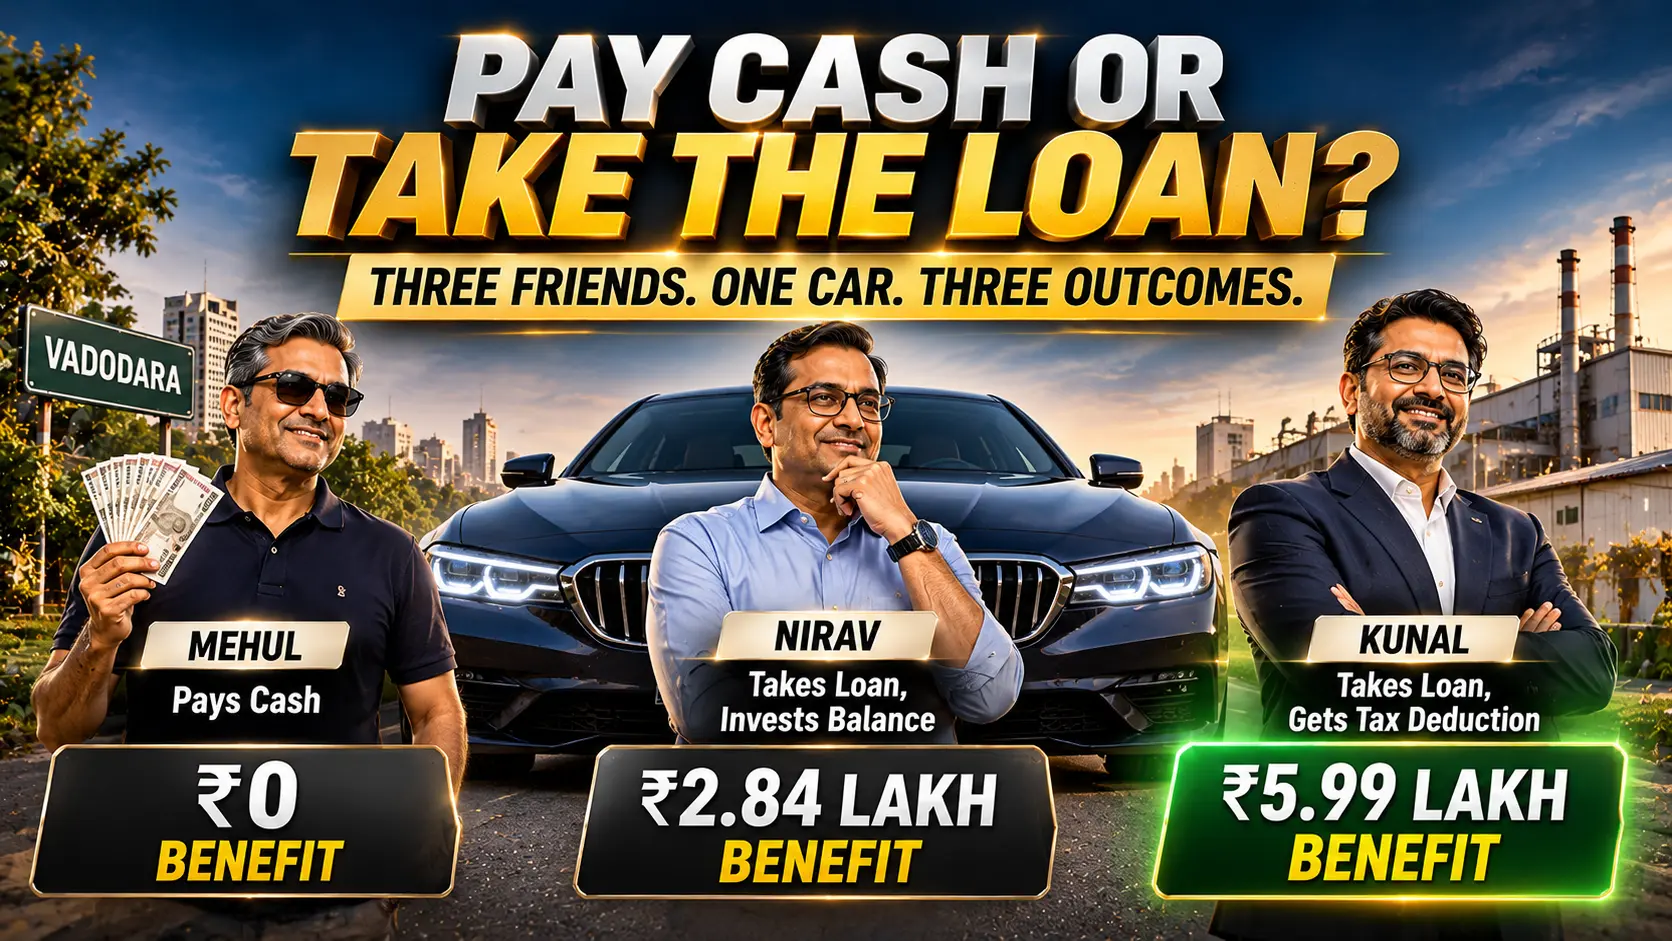
- Nirav, who is salaried, ends up ₹2.84 lakh better off than Mehul after tax, about 5.7% of the car’s price.
- Kunal claims the interest as a business expense, saves ₹3.16 lakh in tax and ends up ₹5.99 lakh ahead, about 12.0% of the car’s price.
- The advantage depends on the assumed 11% return; at roughly 7.5% it disappears, and the EMI is due every month regardless.
- Decide the budget as if paying cash; a loan should not make a bigger car feel affordable.
Table of Contents
Every few months, a client asks us some version of the same question. “I can afford the car. Should I just pay for it, or is there a smarter way?” We decided to answer it properly, with real numbers, using three friends from Vadodara. The friends are made up. The arithmetic is not.
Meet Mehul, Nirav and Kunal
The three of them grew up in the same lane and still meet most Sundays for chai and an argument about cricket. All are in their late forties, all earn a little over ₹2 crore a year, and all file their returns under the new tax regime. Last month, each of them walked into the same showroom and fell for the same car, priced at ₹50 lakh.
Mehul
wrote a cheque. He has never had a loan and sees no reason to begin now.
Nirav
is a senior director at a pharma company, so his income is salary and bonus. He thought it over for a weekend and decided to borrow 80% of the price and keep the rest of his money invested.
Kunal
runs a manufacturing business, and the car will mostly be used for plant visits and client meetings. He also borrows 80%. His accountant has told him the interest can be claimed as a business expense.
Here is what we assumed for all three:
The car costs ₹50,00,000
Nirav and Kunal pay 20% (₹10,00,000) as down payment and borrow ₹40,00,000 at 7.5% for 5 years.
The ₹40 lakh
They did not spend stays invested at 11% a year, and the EMIs are paid out of that money. Mehul has nothing left to invest, because his ₹50 lakh went into the car.
At this income,
The marginal tax rate is 39% (30% slab, 25% surcharge, 4% cess). Gains on equity funds are taxed at 14.95% (12.5%, a surcharge capped at 15%, and 4% cess), after the ₹1.25 lakh exemption.
Kunal uses the car
Only for business. If your own use is mixed, the deduction shrinks in the same proportion.
Mehul: the cheque
Mehul’s story is the shortest. He pays ₹50 lakh, collects the keys and goes home. There is no EMI to remember, no interest to pay and nothing to track. His portfolio, however, is ₹50 lakh lighter, and that money will not compound over the next five years.
There is nothing foolish about this. Plenty of sensible people sleep better with no loan. But since Mehul is our yardstick, we will say it plainly: his benefit from the whole exercise is ₹0. Everything else in this article is measured against him.
Nirav: the loan with no tax help
Nirav pays ₹10 lakh upfront and borrows ₹40 lakh. His EMI comes to ₹80,152 a month, and the table below shows how the numbers work.
Table 1: Nirav and Kunal's loan (before tax)
| Item | Amount (₹) |
|---|---|
| Car price | 50,00,000 |
| Down payment (20%) | 10,00,000 |
| Loan amount | 40,00,000 |
| Monthly EMI (7.5%, 60 months) | 80,152 |
| Total EMIs paid over 5 years | 48,09,120 |
| Total interest paid to the bank | 8,09,120 |
| ₹40,00,000 invested at 11% grows to (after 5 years) | 67,40,232 |
| Less: EMIs paid from this investment (with the growth they would have earned) | 62,86,570 |
| Corpus left after the last EMI | 4,53,662 |
OVER FIVE YEARS
Nirav pays the bank ₹8.09 lakh in interest. In the same period his invested money earns ₹12.63 lakh. The gap of ₹4.54 lakh is what he is ahead of Mehul, before tax.
Then the taxman arrives. The gains on his investment attract about ₹1.70 lakh of tax, which leaves Nirav ₹2.84 lakh better off than Mehul. Because he is salaried, nothing about the loan reduces his tax. The interest is a plain cost. His loan costs him 7.5%, and his investment earns roughly 9.4% after tax on gains. That thin gap of under two percentage points is the entire benefit, which is why it comes to only 5.7% of the car’s price.
Kunal: the same loan, with a tax shield
Kunal’s loan is identical to Nirav’s. Same EMI, same interest, same investment. The only difference is that his interest is a business expense, so every rupee of interest reduces his taxable income, and at his level, a rupee of deduction is worth 39 paise.
Table 2: Interest paid and tax saved each year (Kunal)
| Year | Interest paid (₹) | Tax saved at 39% (₹) |
|---|---|---|
| 1 | 2,76,766 | 1,07,939 |
| 2 | 2,23,581 | 87,197 |
| 3 | 1,66,276 | 64,848 |
| 4 | 1,04,559 | 40,778 |
| 5 | 37,938 | 14,796 |
| Total | 8,09,120 | 3,15,558 |
INTEREST IS HEAVIER IN THE EARLY YEARS, SO THE SAVING IS TOO.
Over the five years Kunal gets back ₹3.16 lakh, which brings the effective cost of his loan down to about 4.6% (7.5% × (1 − 0.39)). Against an 11% investment, that is a much more comfortable gap than Nirav has.
A few things Kunal’s accountant will remind him of. The deduction covers only the business-use share of the car. Depreciation (15% on the block of motor cars) is available whether he pays cash or borrows, so it does not change this comparison. And if he is taxed under presumptive schemes such as Section 44ADA or 44AD, he cannot claim the interest separately at all.
The scoreboard after five years
Here are all three side by side, in rupees, at the end of year 5.
Table 3: What each friend is worth at the end of year 5
(₹, compared with paying cash)
| The three outcomes, side by side | The benefits in perspective | |
|---|---|---|
| Friend | Benefit over Mehul (₹ lakh) | (as a % of the car’s price) |
| Mehul (Pay cash) | ₹0 | 0% |
| Nirav (Loan, no tax help) | ₹2.84 lakh | 5.7% |
| Kunal (Loan + tax shield) | ₹5.99 lakh | 12.0% |
All three drive the same car. Nirav and Kunal also have extra money sitting in their portfolios, and Kunal has more than twice as much as Nirav.
What if the market does not co-operate?
The 11% in our example is an assumption, and markets do not sign contracts. Run the same numbers with a 9% return and Nirav and Kunal are ahead of Mehul by only about ₹1.65 lakh before tax. At roughly 7.5%, the advantage disappears. The EMI, meanwhile, is due every month whether the market is up or down, so the investment must be liquid enough to fund it without selling at a bad time. Nirav, with his thinner margin, has the most reason to worry. Kunal has a cushion from the tax saving.
The showroom trap
While the paperwork is being done, the salesperson leans over to Nirav. “Sir, for just ₹1.12 lakh a month you can have the ₹70 lakh model. The EMI is so small compared to your income.”
It is true that the EMI is small. That is exactly the problem. A loan makes a bigger car feel affordable, and Nirav’s tidy optimisation turns into ordinary spending on something that loses value every year. The gains we have discussed come to a few percent of the car’s price, so a more expensive car costs far more than any loan can ever save.
Everything in this article holds only if you can afford to buy the car in cash and are choosing the loan to optimise.
BEFORE YOU SIGN:
Ask yourself one question. Would I still buy this car if I had to pay for it today, in full? If the answer is no, the loan is not solving a problem. It is hiding one.
What we would tell the three of them
- Mehul (benefit ₹0): Nothing wrong with the cheque. You keep things simple and carry no market risk. Just know that you are giving up roughly ₹2.84 to ₹5.99 lakh that the others will earn.
- Nirav (benefit ₹2.84 lakh): The loan can work, but only if the ₹40 lakh stays invested and actually earns more than the loan costs. If you are likely to spend the money or park it in a savings account, pay cash.
- Kunal (benefit ₹5.99 lakh): The interest deduction makes the loan clearly worth it, subject to how much of the car's use is for business.
Conclusion
ALL THREE:
Decide the budget as if you were paying cash. The loan is a tool for making better use of money you already have.
By CA Aayush Bhatt, Head of Research & Strategy, Ascent Financial Solutions Pvt. Ltd. This article is for educational purposes only and does not constitute investment advice or a recommendation.